Mortgage Rate Predictions for 2026: When Will Mortgage Rates Go Down?


Mortgage rates moved above 7% for the first time last month and are likely to hold steady or rise slightly in October, depending on what happens with inflation and the Federal Reserve’s next meeting. Still, there’s encouraging news: Home sales haven’t fallen off significantly even with elevated rates, thanks in part to builders’ ability to offer incentives and the fact that many parts of the country have become buyer’s markets.
Affordability remains a real challenge for most buyers, however, as home prices and monthly payments remain high.
-
The rate outlook
Expect rates to hover between 6.5% and 7% for the rest of the year and throughout 2027. Understand that the sub-3% rates of the coronavirus pandemic era likely aren’t coming back.
Jump to: LendingTree’s rate forecast.
-
For homebuyers
Buy now if you can afford the payments. Find the right home and plan to stay for at least five years.
Jump to: Should you buy a home this month?
-
For refinancers
Refinance if your current rate is above 7.53%.
Hold off if your rate is below 7.03%.
Jump to: Should I refinance now?
Mortgage rate projections from leading forecasters
Many economic experts think 30-year mortgage rates will stay relatively stable through the end of this year and over the course of 2027.
| Source | Forecast period | Projected rate (30-year loans) |
|---|---|---|
| Fannie Mae | End of 2026 | 6.80% |
| End of 2027 | 6.70% | |
| Wells Fargo | End of 2026 | 6.90% |
| End of 2027 | 6.75% | |
| Mortgage Bankers Association (MBA) | End of 2026 | 6.80% |
| End of 2027 | 6.70% |
Mortgage rates forecast for October 2026: Will interest rates continue to spike?
The short answer: Mortgage interest rates are predicted to rise in October. Expect them to stay elevated — more than double the lows seen in 2021 — and hover around 7%.
Current mortgage rates for October 2026
are averaging:
7.38%
are averaging:
6.27%
What’s been happening with mortgage rates
National average mortgage rates rose over the course of the summer, finally crossing the 7% threshold in late September. Rising rates during this period were in part a reflection of inflation, as well as the Federal Reserve’s decision to increase rates at its meeting on Sept. 17.
“No one should expect rates below 6% anytime soon,” says Matt Schulz, LendingTree’s chief consumer finance analyst. “If inflation remains stubbornly high, it could make it even harder for rates to move lower and provide much-needed relief to the housing market.”
Fannie Mae agrees, predicting average 30-year fixed-rate mortgages will land at 6.8% by the end of the year, according to its latest housing forecast.
It’s near-certain that mortgage rates will remain high compared to the levels seen during the height of the COVID-19 pandemic, when average 30-year mortgage rates were around 2.65%. Those record lows, as nice as they were, might not ever be seen again in our lifetimes.
If 2026 has proved anything to us, it is that none of us has any clue what the future holds. My best advice is to control what you can control. Shop around for prices and rates, be flexible in your search, and don’t forget to breathe. You have more power over rates than you think you do, but you have to take the time to use it.
Should I buy a house now or wait?
Buying may make sense if:
- You can comfortably afford the monthly payment.
- You expect to stay in the home for at least five years.
- You have the flexibility to refinance if rates decline.
Even if rates ease later this year, home prices and competition may increase at the same time, which can offset the benefit of waiting.
Home affordability in October 2026
Home affordability isn’t likely to improve this month. The downward pressure of a buyer’s market may slightly help ease sticker shock, but elevated rates and overall high home prices mean affordability remains tough for most Americans.
The median monthly payment was $2,162 in August 2026, according to the Mortgage Bankers Association’s latest purchase applications payment index.
Mortgage rates aren’t the only thing affecting affordability. Inventory, home prices and seasonal buying trends all influence how expensive it is to purchase a home. That’s why we combine all four into a single affordability grade.
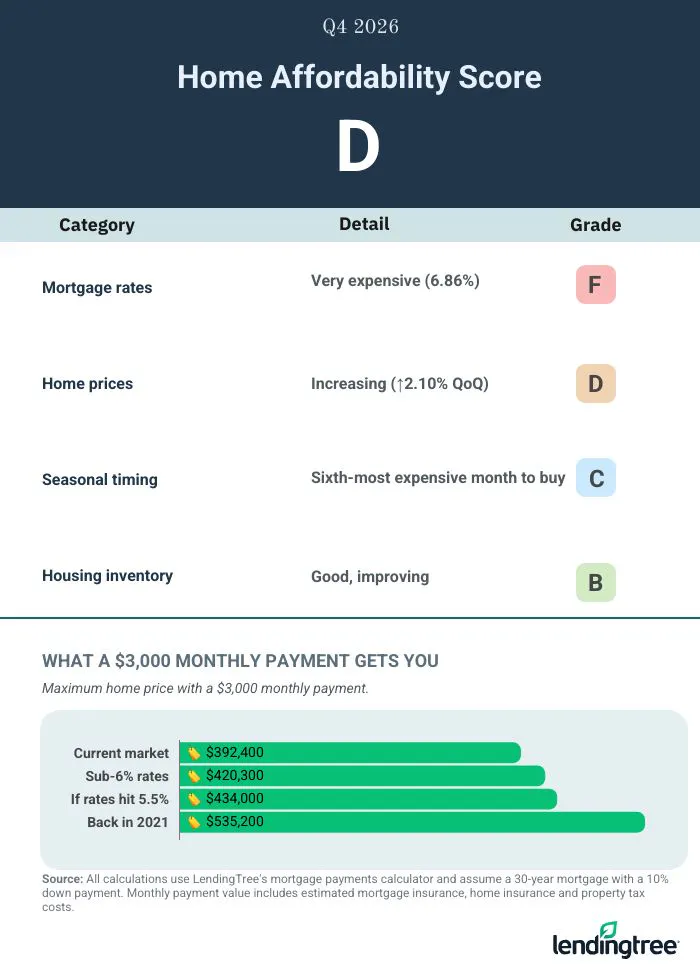
How are these grades calculated? Jump to our affordability grades section to find out.
The Federal Reserve raised rates by 25 basis points at its most recent meeting, and most market experts predict it will hold rates steady at the next meeting on Oct. 27-28 but will raise rates at least one more time this year.
But even if the Fed does raise the federal funds rate, mortgage rates won’t necessarily follow in lockstep. Here’s what you need to know:
- Rate cuts and hikes affect adjustable-rate mortgages (ARMs) directly, but fixed-rate mortgages indirectly.
- Falling mortgage rates can spark rising home prices. If rates do fall, whether the balance will tip toward increased affordability or a troublingly hot housing market remains to be seen.
- Rising mortgage rates are often associated with slower home price growth.
- The Fed may adopt a more aggressive strategy than it did in 2025, in part because a new chairperson took over this spring.
The bottom line for buyers
Don’t wait for perfect conditions. Focus on what you can afford now, shop with multiple lenders for the best rate, and take advantage of available pricing benefits if you’re ready to buy. Schulz urges homebuyers to negotiate their mortgage rates and fees, and notes that a buyer’s market can give you a little extra bargaining power.
Should you refinance in October 2026?
For most homeowners, refinancing only makes sense if you’re saving at least 0.50% on your interest rate and plan to stay in the home long enough to recoup closing costs.
Because rates will likely rise over the remainder of the year, there may not be a clear “best” time to refinance. Instead of trying to time the market, it’s more effective to calculate your break-even point and determine whether refinancing makes sense for your current timeline.
Expert advice on when to refinance
It’s typically smart to hold off on a refinance until you can qualify for a rate that’s at least 50 basis points
Does refinancing make sense for you now?
| Your current rate | Recommendation | Notes |
|---|---|---|
| 7.53% to 7.78% or higher | Refinance now | You could save significantly by refinancing. This is the sweet spot where the rate difference (at least 50 basis points) makes refinancing worthwhile despite closing costs. |
| 7.04% to 7.52% | Compare offers, but expect modest gains | You’re in the same range as current refinance rates. You might save $50 to $100/month, depending on your loan size, but closing costs could take several years to recoup. |
| Below 7.03% | Wait | You already have an excellent rate. Refinancing now would likely increase your rate, not lower it. |
Current refinance rates for October 2026
30-year Refinance Rates
are averaging:
7.65%
15-year Refinance Rates
are averaging:
6.83%
Special circumstances in which you should consider a refinance
Even if your rate is lower than 7.03%, refinancing might make sense in these situations:
- Converting an ARM to a fixed-rate loan. If you have an adjustable-rate mortgage that’s about to reset or you want payment stability, refinancing to a fixed rate locks in predictability even if the rate is slightly higher than your current ARM.
- Cash-out refinance. Need funds for home improvements, debt consolidation or other major expenses? A cash-out refinance lets you tap your home equity. Just ensure the new interest rate and payment still fit your budget.
- Shortening your loan term. Moving from a 30-year to a 15-year mortgage means higher monthly payments but significantly less interest over the life of the loan.
- Financial emergency. If you’re facing financial hardship and even modest savings would make a real difference in your monthly budget, don’t wait for perfect conditions. Act on the savings you can achieve now.
How we calculate our affordability grades
Think of this like a report card for the housing market. We grade four factors — rates, prices, inventory and seasonal timing — then combine them to provide a snapshot of overall housing affordability. The better the grade, the easier it is to afford a home right now.
A: 3.48% or less
B: 3.49% to 3.89%
C: 3.90% to 4.52%
D: 4.53% to 6.58%
F: 6.59% and above
Data source: Freddie Mac Primary Mortgage Market Survey®
A: 0.07% or lower (Excellent/large decrease)
B: 0.79% to 0.08% (Good/slight decrease)
C: 1.99% to 0.80% (Fair)
D: 3.01% to 2.00% (Expensive)
F: 3.02% or higher (Very expensive)
Data source: S&P Cotality Case-Shiller U.S. National Home Price Index, via the Federal Reserve Bank of St. Louis
A: 1,211,611 or higher (Excellent, balanced)
B: 1,044,928 to 1,211,610 (Good, improving)
C: 794,751 to 1,044,927 (Fair, modest improvement)
D: 613,524 to 794,750 (Poor, declining)
F: 613,523 or less (Declining sharply)
Data source: Housing Inventory: Active Listing Count in the United States from Realtor.com, via the Federal Reserve Bank of St. Louis
A: January and February
B: March, September, November and December
C: April, July, August and October
D: May and June
F: Unforeseen or extreme events
Data source: LendingTree analysis: “The $23,000 Secret: January Is the Cheapest Month to Buy a Home”
For each factor we assessed, we then assigned a point value to the grade:
A = 4.0 points
B = 3.0 points
C = 2.0 points
D = 1.0 points
F = 0.0 points
Then, we weigh the sub-scores to arrive at a final grade, since all factors aren’t equally important:
| Category | Weight | Rationale |
|---|---|---|
| Mortgage rates | 35% | Rates have the biggest impact on your monthly payment and long-term costs. |
| Home prices | 35% | Home prices directly determine affordability and how much income you’ll need to bring to the table. |
| Housing inventory | 20% | Inventory affects your options when shopping, and can affect your ability to negotiate in the homebuying process, but doesn't radically change baseline affordability. |
| Seasonal timing | 10% | Seasonality has a minor effect on prices and can change from year to year. |
We then give the final score a grade:
3.26 to 4.00 = A
2.51 to 3.25 = B
1.51 to 2.50 = C
0.76 to 1.50 = D
0 to 0.75 = F
Frequently asked questions
In today’s market, any rate below 7.03% is better than the national average. That said, your best rate is unique to you, your financial profile and the exact mortgage type you want to borrow. Use LendingTree to find your best offer — when banks compete, you win.
Mortgage rates are unlikely to go down to 5% in 2026. And, due to high inflation and other economic factors, LendingTree’s experts don’t predict rates will drop below the 6% threshold any time soon, either.
It’s impossible to say for certain, but our market experts aren’t expecting rates anywhere near 3% for the foreseeable future. In general, experts seem to agree that rates will hover between 6.5% and 7% for most of the next few years.
You can expect to pay around $3,409 per month for a $400,000 mortgage loan near today’s average rates with a 30-year repayment term. Of course, the exact amount will change depending on your financial profile and the market conditions when you take out your loan.
In the summer of 2025, buying an existing home was more expensive than building a new one for the first time since 1989, according to the National Association of Home Builders. The trend had reversed itself by the end of the year, however, and new builds were once again more expensive per square foot than existing homes.
There is some evidence that buyers of newly constructed homes get more opportunities to reduce costs, both through builder incentives and mortgage rate buydowns.
Explore whether it’s better to rent or buy in today’s market.
“There’s no reason to think that the housing market is going to crash anytime soon,” Schulz says. Low unemployment and foreclosure rates, as well as a moderate housing inventory increase, are all signs that the housing market is relatively healthy, he adds.
And, if you’re thinking a housing market crash could even bring some benefits — like lower home prices — he offers this reminder: “These things don’t happen in a vacuum. A housing market crash very well might be accompanied by a recession, for example. That would likely mean increased unemployment and greater overall economic uncertainty, leaving people even less able to afford to buy.”
A mortgage interest rate is the base rate you’re charged to borrow money, but a mortgage annual percentage rate (APR) is the total cost of taking out a mortgage (the interest rate plus closing costs and fees). Both numbers are expressed as a percentage. For more details, check out our guide to distinguishing an APR versus an interest rate.
Mortgage rates dropped to a historic low of 2.65% in January 2021, when the Federal Reserve cut the federal funds rate to 0% to stabilize the post-pandemic economy.
Haggle for a lower interest rate by using your mortgage offers as leverage. Ask each lender about matching your lowest quoted rate. Consider making a larger down payment, select an ARM loan with a lower initial rate or ask your lender about your mortgage buydown options.
View mortgage loan offers from up to 5 lenders in minutes