Auto Loan Resources
Your guide to loans for cars, RVs and boats


Advertising Disclosures
Loading Disclosures…
You need a loan you can afford for the vehicle you want. Our experts can help you understand your options and how to make the numbers work for you.
Explore auto loan types
Auto loans
You don’t have to take the dealer’s offer. Shopping lenders could save you an average of $3,064.
Bad credit car loans
It’s possible to get a car loan with bad credit. Explore reputable lenders and how to improve your odds.
Private party car loans
Skip the dealership and find a lender that offers loans for private car sales.
Lease buyout loans
Keeping the car you love could cost less than you expect. See if you can get a better rate on your lease buyout loan.
Boat loans
Wondering if you have boat money? The right boat loan can make ownership more affordable.
RV loans
When you save on your loan with a lower rate, there’s room in your budget for adventure.
Looking to lower your monthly payment? See LendingTree’s auto refinance resources.
Compare your options
Lease or buy?
Lease for flexibility. Buy for long-term value.
New or used?
Buying used can save you money, but it comes with more uncertainty.
Get prequalified or preapproved?
Prequalification shows you where you stand. Preapproval gives you real numbers and negotiating power.
0% APR or cash back?
Don’t assume that 0% is always the best deal.
Cosigner or solo?
Cosigners can make your loan cheaper and easier to get, but they take on risk.
Rates & market insights
How much will your car payment actually cost? We’ve got you covered. See real average rates based on hundreds of thousands of loan requests on our platform.
Find the average rate for your credit in the table below and plug it into our auto loan calculator for an estimate.
| Credit score range | Average new car APR | Average used car APR |
|---|---|---|
| Excellent (800 and above) | 5.34% | 10.18% |
| Very good (740-799) | 5.48% | 8.41% |
| Good (670-739) | 12.88% | 12.47% |
| Fair (580-669) | 18.47% | 20.36% |
| Poor (Under 580) | 21.50% | 23.02% |
Insights from LendingTree research:
- Watch out for long loan terms. Borrowers with loans longer than six years pay nearly $6,000 more on average.
- Want a small loan? You’re not alone. More than a third of people with active auto loans borrowed less than $25,000. It’s a popular move among Gen Z and borrowers with bad credit.
- Used car prices aren’t always a steal. People nationwide are seeking loans for used cars priced at a median of $1,350 above wholesale value. Older and premium cars are marked up more aggressively.
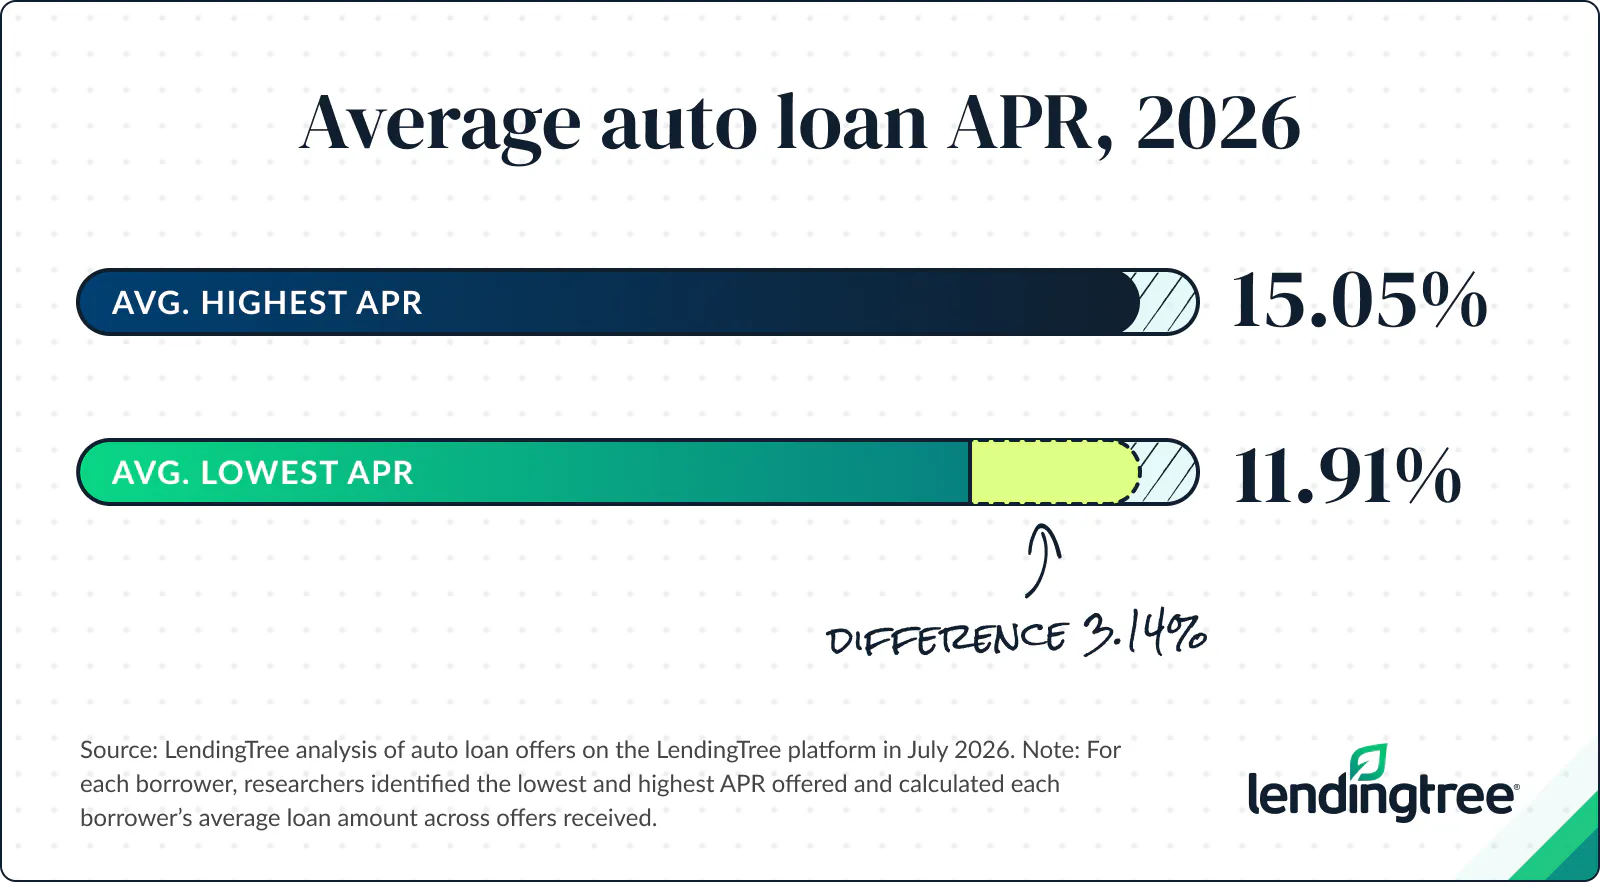
- Lenders compete. You save. Shopping around for a car loan on LendingTree could save users an average of $3,064 by choosing the offer with the lowest APR over the highest. See average offer APRs below.
Helpful tools & calculators
Estimate how much your car loan could cost in dollars and cents.
See how much car you can afford before you start shopping.
People with credit scores of 661+ get better rates and odds of approval. See where you stand with the LendingTree app.
Expert guides
Get approved
How to get a car loan
We’ll walk you through the process, step-by-step.
What you need to finance a car
Prepare the documents lenders request during the application process.
How to get a car loan with no credit history
It’s not easy to get a car loan without a history of credit, but there are ways to meaningfully improve your chances.
Save money
Dealer fees to watch out for when buying a car
Wondering about doc and origination fees, and which are negotiable? Learn what you can push back on and what’s set in stone.
5 ways to get a smaller car loan
Review five strategies to get a smaller loan — and cheaper monthly payments.
What is the 20/4/10 rule for car buying?
This classic car advice helps you protect your finances — both now and in the future.
Buy with confidence
How to buy a car the smarter (and cheaper) way
Experts weigh in on what they wish everybody knew about saving money on car purchases.
Questions to ask when financing a car
Don’t show up to the dealership empty-handed — use our questions to make sure you’re not getting a lemon.
How much should a down payment be on a car?
10%? 20%? More? Find out how much you should put down based on your situation.
Reviews & best providers
Learn more about how we pick the best auto loan lenders.
Ready to compare?
See auto loan offers with LendingTree
You could save an average of $3,064 on your car loan by choosing the offer with the lowest APR rather than the highest. LendingTree makes it easy. Instead of applying to just one lender and hoping for a good rate, see multiple lenders compete for your business — so you can choose the best offer.
1. Tell us what you need
Take two minutes to tell us who you are and how much money you need for your vehicle — we’ll take care of the rest. It’s free, simple and secure.
2. Shop your offers
We’ll send you offers from up to five trusted lenders. Compare your offers side by side to see which one will save you the most money.
3. Get your money
Finalize your loan with your lender, and you’ll be on the road in no time. You could see money in your account in as soon as 24 hours.
Frequently asked questions
There’s no universal score you need to get a car loan, but generally, lenders look for borrowers with scores of 661 or higher.
Yes, but the effect can be small and temporary. Your credit score can dip when your lender does a hard credit pull. But it should recover quickly if you stay on top of payments and are otherwise responsible with your credit.
Your car loan should be as short as you can make it while keeping monthly payments in your budget. Long car loans cost more in interest over the life of the loan, and nearly 62% of borrowers with defaulted loans had loan terms of 72 months or longer.
It’s possible, but it comes with big risks. Zero-down bad-credit car loans come with high rates and increase your odds of going upside down on your car loan, or owing more than it’s worth.
You should finance wherever you can get the best deal. You can shop for loans online first, then compare the offer you get from the dealership.
Yes. Learn how to counter tactics from car salespeople and tips to negotiate a car price before you set foot in the dealership
Yes. You may be able to pay off your car loan faster by refinancing, making early payments toward the principal and canceling any unnecessary add-ons.
Getting out of a car loan you can’t afford is possible, but it’s not always easy. If you’re looking for a car loan now, try to keep your payments as cheap as possible to avoid stretching your budget too far.
You can sell your car that still has a loan in a private sale — you could get the cash you need to pay off the loan by selling privately — or trade your car in at the dealership.
It’s possible to back out after financing, but not every lender or dealership will allow it. Your best bet is to take your time finding a car and a loan that fits your budget.